Fast Home Sale in Huntsville: Compare Your Options
Compare listing with an agent against a direct cash sale. Get a written cash offer within 24 hours of our visit, from a local buyer with 30 years of experience. We buy houses in any condition.
Fast Home Sale in Huntsville: Choose the Path That Fits
We’re Huntsville House Buyer AL, and we’ve been buying houses in Madison County for 30 years. We’ve seen every kind of situation, and we’ll tell you honestly when listing is the better route.
Your home’s condition matters. So does whether you need a predictable move or have time to test the market.
List with an agent or sell directly for cash?
A good agent can put your house in front of more buyers, and for a house in solid shape with time on your side, that’s often the right call. But getting ready may mean repairs, cleaning, photographs, and repeated showings. After an offer, inspections and buyer financing can still affect the schedule.
A direct cash sale removes the buyer’s mortgage approval step. You may trade some potential sale price for less preparation and fewer complications. Neither route automatically leaves you with more money.
When an as-is cash sale can save time
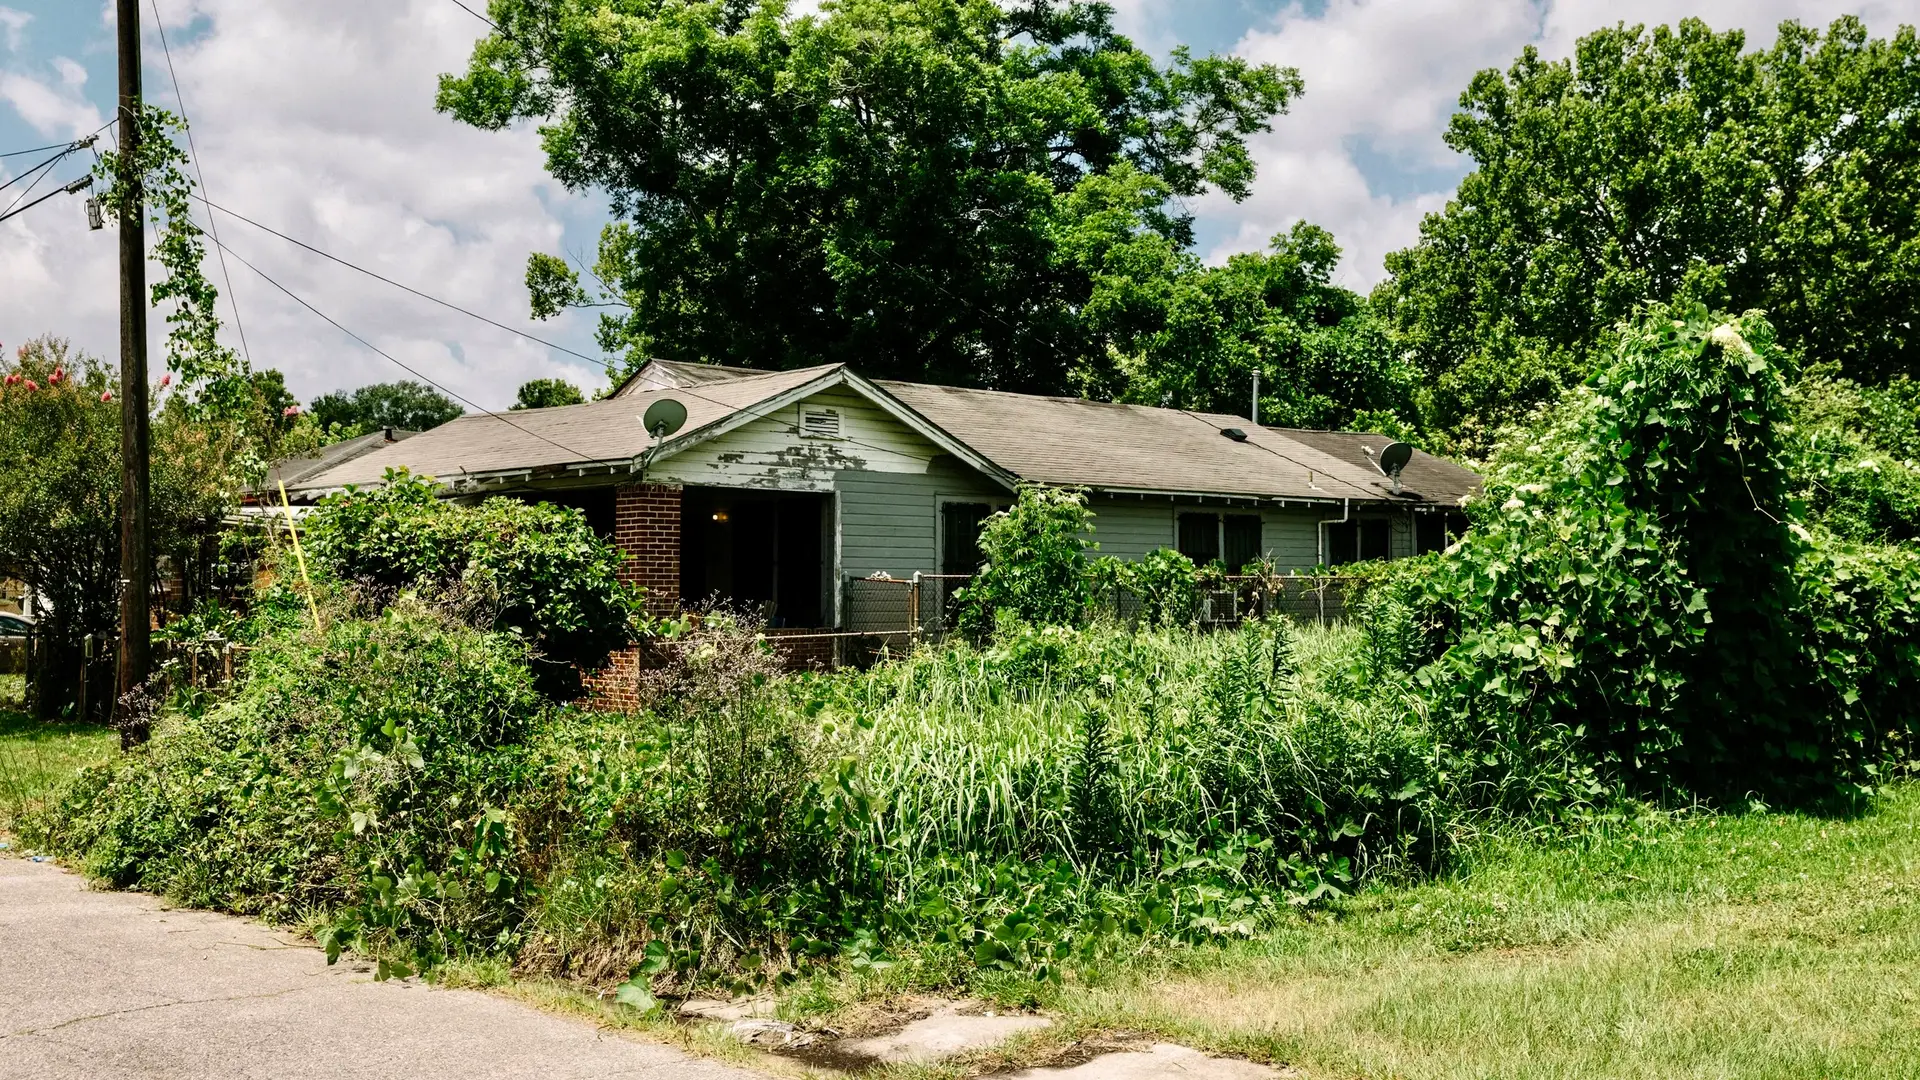
A damaged roof, a fire-damaged house, a hoarder house, or a vacant inherited property can turn preparation into a project you don’t have time to manage. And every contractor appointment pushes the next decision back.
We buy Huntsville and Madison County houses as-is, with no repairs or cleaning required. Our offers cost nothing and carry no obligation. Selling your house as-is may fit when avoiding that work matters more than testing the open market.
How a Fast Home Sale Works in Huntsville
First, contact us with the property address and your situation. We go over the details with you by phone, then arrange a visit. Our home-buying process includes a written cash offer within 24 hours of our visit, not the first call. If we miss that window, we pay you $250.
What to gather before requesting an offer
Have the basics ready:
- The address and any known repair issues.
- Mortgage balances, lien notices, or back-tax information.
- Ownership, estate, or probate papers, if they apply.
Don’t have everything? Start with what you know. Missing documents can affect timing, but you don’t need a perfect file to ask about your options.
What happens between offer and closing
Once you receive the written offer, take your time to review it. Ask questions before signing. If you accept, you pick the closing date, and we begin the closing work. If closing runs late because of us, we pay you $100 a day.
A closing attorney checks ownership and debts tied to the property and handles the closing paperwork. Mortgage payoffs, liens, probate, or title problems may take longer to resolve than the property visit. A quick offer doesn’t mean every closing obstacle is gone.
Compare the Offer With Your Likely Costs and Net Proceeds
An offer tells you the purchase price. Your net proceeds are what’s left after the sale’s expenses and debts are paid.
Count the costs of each sale path
For a listing, account for any negotiated agent compensation, repairs, cleaning, and seller-paid closing costs. Add the cost of keeping the house while it sells: mortgage interest, taxes, insurance, utilities, and upkeep.
Then subtract mortgage and lien payoffs. Those debts don’t disappear because the buyer pays cash. Costs vary by property and contract, so compare written estimates for both paths. A higher price can leave you with less money if getting there costs a lot.
Ask how the cash offer was calculated
Ask which repairs, comparable sales, and resale assumptions shaped the number. You should understand why the offer is what it is.
We explain how we calculate cash offers line by line, including condition, expected repair and cleanup costs, location, and estimated resale value. We also pay all closing costs. Mortgage balances and other debts still affect what you receive.
The useful comparison is the amount left over, along with the time and work required.
Plan for Repairs, Inherited Homes, Foreclosure, and Other Selling Challenges
Damage, code notices, and a house full of belongings create different problems. A cash buyer may accept the property’s condition, but ownership and legal issues still need attention.
Decide which work you can leave behind
With fire damage or major repairs, start by deciding whether you can fund and manage the work. A difficult cleanout adds labor, hauling, and time before a listing is ready.
An as-is sale can remove those preparation tasks. It doesn’t erase code notices or legal obligations, so bring those papers into the conversation early.
Handle ownership, probate, and urgent deadlines early
Identify everyone who owns the house. For inherited property, gather the will, estate papers, and any court documents. A probate attorney can explain who has authority to sell and what court steps apply.
Facing foreclosure? Contact your mortgage servicer and a qualified attorney promptly. The CFPB’s loss mitigation procedures govern how servicers handle certain requests for foreclosure alternatives. An offer or signed sale contract doesn’t automatically stop proceedings.
Don’t build your plan around time you may not have.
Choose the Sale You Can Carry Through
The right sale fits your deadline, your home’s condition, and the work you can take on. Compare what you’ll keep, not just the number on the offer. Then weigh that against the cost of waiting.
If selling as-is fits, call us at 256-858-7464 or request your no-cost, no-obligation cash offer. We buy houses in any condition in Huntsville and Madison County, and you’ll have a written offer within 24 hours of our visit.
Frequently Asked Questions
You’ll have a written cash offer within 24 hours of our visit. We go over the details by phone first, then arrange the visit. If we miss that window, we pay you $250.
No. We buy Huntsville and Madison County houses as-is. An as-is sale doesn’t erase code notices or legal obligations, so bring those papers up early.
We buy foreclosure and probate houses. Ownership and legal steps still need attention, so contact your mortgage servicer and a qualified attorney promptly. An offer or signed contract doesn’t automatically stop foreclosure proceedings.
We pay all closing costs, and you pick the closing date. Mortgage payoffs and liens still come out of what you receive. If closing runs late because of us, we pay you $100 a day.
No. A good agent can bring more buyers when your house is in solid shape and you have time. A cash sale can save time and preparation but may mean a lower price. Compare your net proceeds for both.
- We Buy Houses As-Is
- Locally Owned and Operated
- 30 Years Buying Houses in Madison County
- Fair Cash Offers, No Obligation
Related Help for Huntsville Homeowners
If this sounds like your situation, these pages can help: