Pre-Foreclosure Home Buying in Huntsville: Sell Before the Sale Date
Need to sell a house in foreclosure in Huntsville? We’ve bought houses here for 30 years, and we can give you a fair cash offer within 24 hours of our visit. No repairs, no cleaning. We can often close before the sale date.
On this page
- Deciding Whether to Sell Before the Foreclosure Sale Date
- Checking for Liens, Back Taxes, and Title Problems Before You Sell
- Selling a Pre-Foreclosure House That Needs Repairs
- How the Cash Offer and Closing Process Works
- When a Traditional Sale or Loan Modification Makes More Sense
- Frequently Asked Questions
Deciding Whether to Sell Before the Foreclosure Sale Date
The real question is which path leaves you in the best spot before the sale date. Start with three numbers from your lender:
- Your full mortgage payoff
- How much you’re behind, with fees
- The foreclosure sale date
A quick cash sale usually fits when the house needs work you can’t pay for, the date is too close to list, or you just want it done. With us, we pay all closing costs and you sell as-is. Your mortgage is paid off at closing, and what’s left is yours.
If you fell behind for a short-term reason and can catch up, you may not need us at all. We’ll tell you that.
Checking for Liens, Back Taxes, and Title Problems Before You Sell
Your mortgage usually isn’t the only thing tied to the house. Before closing, every debt on it has to be paid. Common ones:
- A second mortgage or home equity line
- Unpaid property taxes
- Court judgment or contractor liens
- Unpaid HOA dues
Title problems are about who can sell, like a name on the deed of someone who passed away. With us, any mortgages, liens, back taxes, or title issues are explained before you sign. If a death in the family is involved, see our probate property buying page.
Selling a Pre-Foreclosure House That Needs Repairs
If the house needs work, stop spending money on it. Repairs take bids, contractors, and permits, and the sale date won’t wait. Don’t borrow money for repairs or start a remodel you can’t finish.
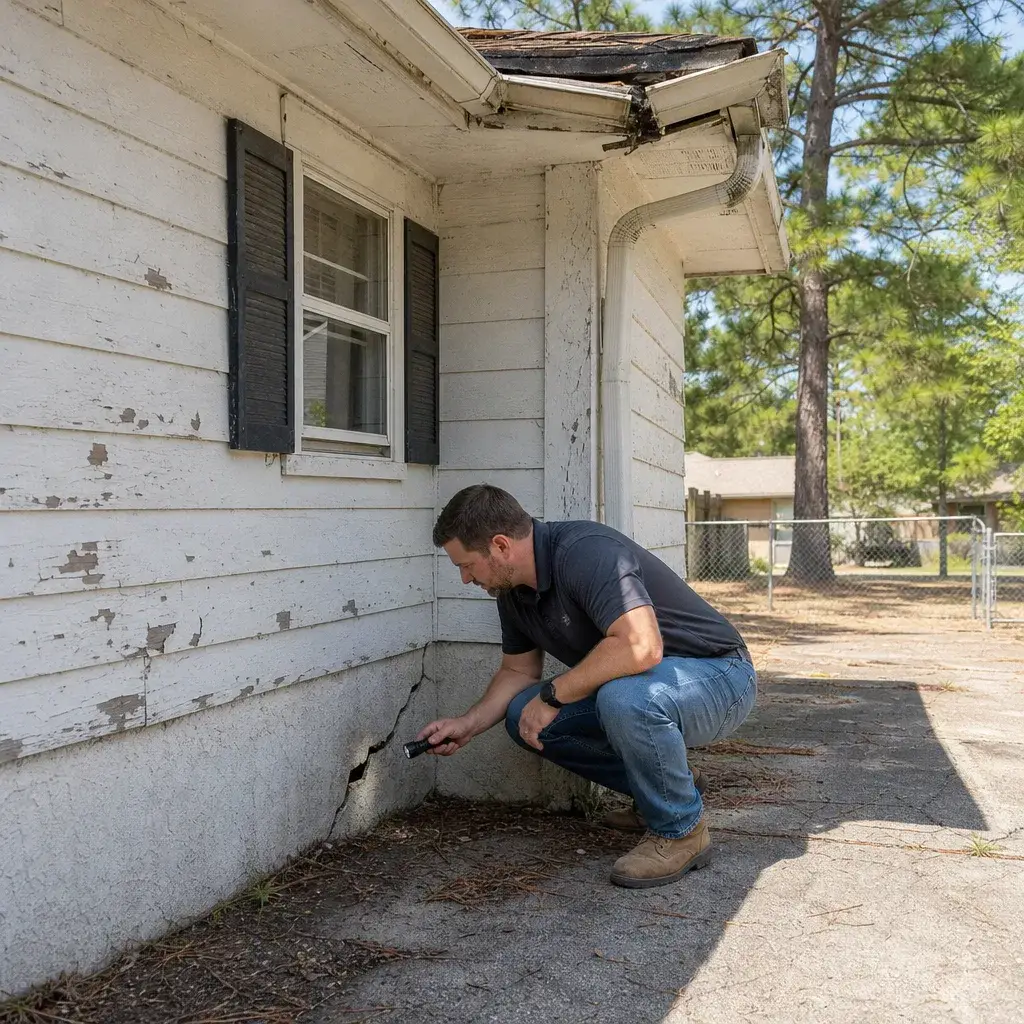
Do keep the house locked and insured. Then tell us what you know, like roof leaks, foundation cracks, or code letters. The condition is part of our offer, not a reason to turn you away. Big problems like fire damage or a hoarder house are fine too.
How the Cash Offer and Closing Process Works
The process is short on purpose:
- You tell us about the house and your sale date.
- Jason looks at the house. It’s no-obligation.
- You get a cash offer within 24 hours of our visit, showing how your payoff is handled.
- You decide, with time to ask questions.
- We close. Your lender is paid at closing, the rest goes to you, and we pay all closing costs.
Keep opening your lender’s mail until closing. Jason has bought houses in Huntsville and Madison County for 30 years, and we’re proud members of the Huntsville/Madison County Chamber.
When a Traditional Sale or Loan Modification Makes More Sense
A cash sale isn’t for everyone. If your income is steady again and you want to keep the house, talk to your lender about a repayment plan, loan modification, or forbearance. A HUD-approved housing counselor can help you fill out the forms for free.
Listing with an agent may fit better if the house is in good shape, you owe a lot less than it’s worth, and the sale date is far enough away. If one of those paths keeps you home or leaves you more money, take it.
Frequently Asked Questions
Paying off your loan through a sale before the auction date generally looks better on your credit history than a completed foreclosure. A completed foreclosure stays on your credit report and can make it harder to qualify for a new mortgage for several years. Selling and paying off the loan on your own terms closes the account instead of leaving a foreclosure mark behind. Either way, talk with your lender about how they will report the payoff once closing happens.
Any second mortgage or home equity line of credit gets paid off from the sale proceeds at closing, just like your first mortgage. This is common. Many homeowners forget about a HELOC they rarely used, and it shows up once a title search is done. It does not stop a sale, but it does reduce what you walk away with, so it is worth checking your records early.
Yes, you can still move forward even if you’re unsure who’s on the deed, because that gets sorted out before anything is finalized. This comes up often after a divorce, a death in the family, or when names are spelled differently across old paperwork. Pulling together your deed and any related papers you have gives a clearer starting point, and any title questions get reviewed and explained before you sign a purchase agreement.
- We Buy Houses As-Is
- Locally Owned and Operated
- 30 Years Buying Houses in Madison County
- Fair Cash Offers, No Obligation
Other Houses We Buy in Huntsville
We buy houses in any condition across Huntsville and Madison County. Here are the other situations we help with:
- We buy fire-damaged houses in Huntsville
- We buy hoarder houses in Huntsville
- We buy inherited houses in Huntsville
- We buy probate houses in Huntsville
- We buy houses with major damage in Huntsville
- We buy houses with code violations in Huntsville
- We buy vacant houses in Huntsville
- We buy rental properties in Huntsville
Helpful guides for your situation:
- Behind on Your Mortgage in Huntsville? Your Options Before Foreclosure
- What Is the Fastest Way to Stop Foreclosure in Huntsville? (2026)
- Can You Sell a House in Foreclosure in Huntsville? (2026 Guide)
- What Is the 37-Day Foreclosure Rule and How Does It Affect You?
- How our home buying process works
- Pre-Foreclosure in Huntsville: How to Sell Before the Sale Date
- See our reviews from Huntsville sellers