When Does a Cash Sale Make Sense in Huntsville?
A fair cash offer within 24 hours of our visit, from a local buyer with 30 years of experience. We buy houses in any condition.
Deciding If a Fast Cash Sale Fits Your Situation
Selling for cash isn’t right for everyone. It’s a trade. You may give up some of the price you could get on the open market. In return, you skip the repairs, the cleanup, the showings, and the waiting. The real question is whether that trade makes sense for you right now.
A cash sale usually fits when:
- The house needs big repairs. Fire damage, water damage, a worn-out roof, or foundation trouble can make a home hard to sell the usual way. We buy as-is, so you don’t fix or clean a thing.
- You inherited a house you don’t plan to keep. Maybe it’s still full of a parent’s things, and going through it all feels like too much. You don’t have to empty it first. If it’s still in probate, that’s okay. We buy probate properties too.
- The house is packed with belongings or has turned into a hoarder situation, and you can’t face clearing it out.
- You’re behind on payments or worried about foreclosure. Any mortgages, liens, back taxes, or title issues are reviewed and explained before you sign anything.
- The house is sitting empty or has code violations, and the bills and worry keep piling up.
- Life changed fast, like a new job, a health problem, or a family change, and you need a clear closing date you can plan around.
A cash sale probably isn’t your best move when:
- Your home is updated, clean, and would show well. A buyer using a mortgage may pay more for it, and a good local Realtor can help you get that price.
- You aren’t in a hurry and don’t mind a few months of showings and open houses.
- You need a set number no matter what. Our offers depend on the home’s location, condition, size, comparable sales, market demand, needed repairs, cleanup costs, and estimated resale value. Major structural, fire, water, or foundation damage may lower the offer. If you have to hit a certain payoff amount, a cash offer may not reach it.
If you’re stuck in the middle, try this. Add up what it would cost to get the house ready to list: repairs, cleanup, and the mortgage, taxes, insurance, and utilities you’d keep paying while it sits. Then hold that next to a cash offer where we pay all closing costs and you close on a date that works for you. Seeing both numbers side by side tends to make the answer clear.
Getting our number won’t cost you anything. The visit and offer are free, and you’ll have a written offer within 24 hours of our visit. Jason has 30 years of experience buying houses in Huntsville and Madison County, and his construction background helps him size up repairs. Take the offer, show it to your family or a Realtor, and decide with no pressure from us.
Problem Properties That Are Hardest to Sell the Traditional Way
Some houses aren’t hard to sell because of the market. They’re hard to sell because of what’s going on inside them. Most buyers need a loan, and a loan usually comes with an appraisal and an inspection. A house with serious damage can stop the deal right there, sometimes weeks after you thought it was done.
Fire-damaged houses are often the toughest. Smoke gets into the walls, wiring, ductwork, and framing, so the smell and the damage go deeper than what you can see. A lot of lenders won’t fund a home that isn’t livable, and repairs usually need permits and inspections before anyone can move back in. Jason’s background in home building and construction helps him read past the soot to what the house really needs, so we can make a fair offer on it as it stands.
Hoarder houses are hard to show and hard to inspect. Piles of belongings can hide leaks, pests, rotted floors, or mold, and buyers tend to imagine the worst. A full cleanout can take weeks and cost real money before you even list. Many families also feel embarrassed letting strangers walk through. We buy as-is, so nobody has to clear a single room first.
Inherited houses come with a different kind of weight. The heirs may live far away or not agree on what to do. Someone still has to pay the taxes, insurance, and utilities while the house sits. If it’s going through probate, the person handling the estate needs the legal authority to sign before anyone can sell. On our purchases, a closing attorney handles the closing, and any title issues are reviewed and explained before you sign the purchase agreement.
Houses with major repairs scare off a lot of regular buyers. Here’s how it often goes:
- Foundation cracks or sloping floors show up on the inspection report, and the buyer backs out.
- An old roof or past water damage leads to a long list of repair requests you can’t afford to cover.
- The appraisal comes in low because of the condition, and the loan falls short of the price you agreed on.
- The house goes back on the market, and the next buyer finds the same problems.
Code violation properties and vacant houses stack up costs in quieter ways. City notices and deadlines keep coming. Empty homes can be harder to insure, and they can draw break-ins or squatters. Every month the house sits, you’re paying to own something you don’t use.
Pre-foreclosure adds a clock on top of everything else. A traditional sale can take longer than you have, and a deal that falls apart late can leave you with even less time. Any mortgages, liens, or back taxes are reviewed and explained before you sign, so you know where you stand.
Each of these situations has more than one path. The choices for inherited, fire-damaged, or problem properties in Huntsville range from fixing and listing to renting to selling as-is. What they share is simple. The things that scare off a lender or a buyer with a mortgage don’t stop a cash buyer who plans to do the repair work. That’s why a house that’s stalled on the open market can still sell quickly and cleanly in a cash sale.
Selling an Inherited or Probate Property
Yes, you can sell an inherited house for cash, even if it’s still going through probate. The two things that matter most are making sure the right person can sign and getting the family to agree on a plan. Once those are in place, we can buy the house as-is, with belongings still inside, and close on a date that fits the estate’s timeline.
Start by figuring out who’s in charge. The person handling the estate needs legal authority before a sale can close. If there’s a will, it usually names that person. If there isn’t a will, or you’re not sure which papers you have, a probate attorney can tell you what you need. You don’t have to wait for every answer before you learn what the house is worth. Our visit and offer are free and come with no obligation, so having a real number early can help the family plan.
It also helps to pull these papers together before you talk to anyone about selling:
- A few copies of the death certificate
- The will, if there is one
- Any court papers that name the executor or personal representative
- The latest mortgage statement, if the house still has a loan
- The most recent property tax bill
- Insurance and utility account details
- Keys, garage remotes, and any alarm codes
Next, get everyone on the same page. Inherited homes often go to more than one person. One sibling may want to keep the house, another may want to sell quickly, and a third may live too far away to help. A written offer gives everyone the same number to look at, and you’ll have it within 24 hours of our visit. Share it with your brothers and sisters, the estate’s attorney, or a Realtor you trust, and take the time you need to talk it over.
Then there’s everything inside the house. This part is often the hardest, and it’s usually more about feelings than furniture. You don’t have to empty the place before you sell. Go through it at your own pace and take the photos, papers, and keepsakes that matter to your family. Our sale is as-is, with no repairs or cleaning required, so whatever’s left can stay where it is.
Keep an eye on the monthly costs while you decide. Taxes, insurance, utilities, and yard care keep coming whether anyone lives there or not. If the house still has a mortgage, those payments keep coming too. Any mortgages, liens, or back taxes are reviewed and explained before you sign, so you’ll know what has to be paid off at closing. We pay all closing costs, and you can choose a flexible closing date that lines up with when the estate is ready.
Many inherited homes have been lived in by the same person for decades and have never been updated. That doesn’t scare us. Jason has 30 years of experience buying houses in Huntsville and Madison County, and his background in building and construction helps him look past the dated kitchen and the worn carpet to what the house really needs. That’s how we make a fair offer on the house just as your loved one left it.
Selling Before a Foreclosure Deadline
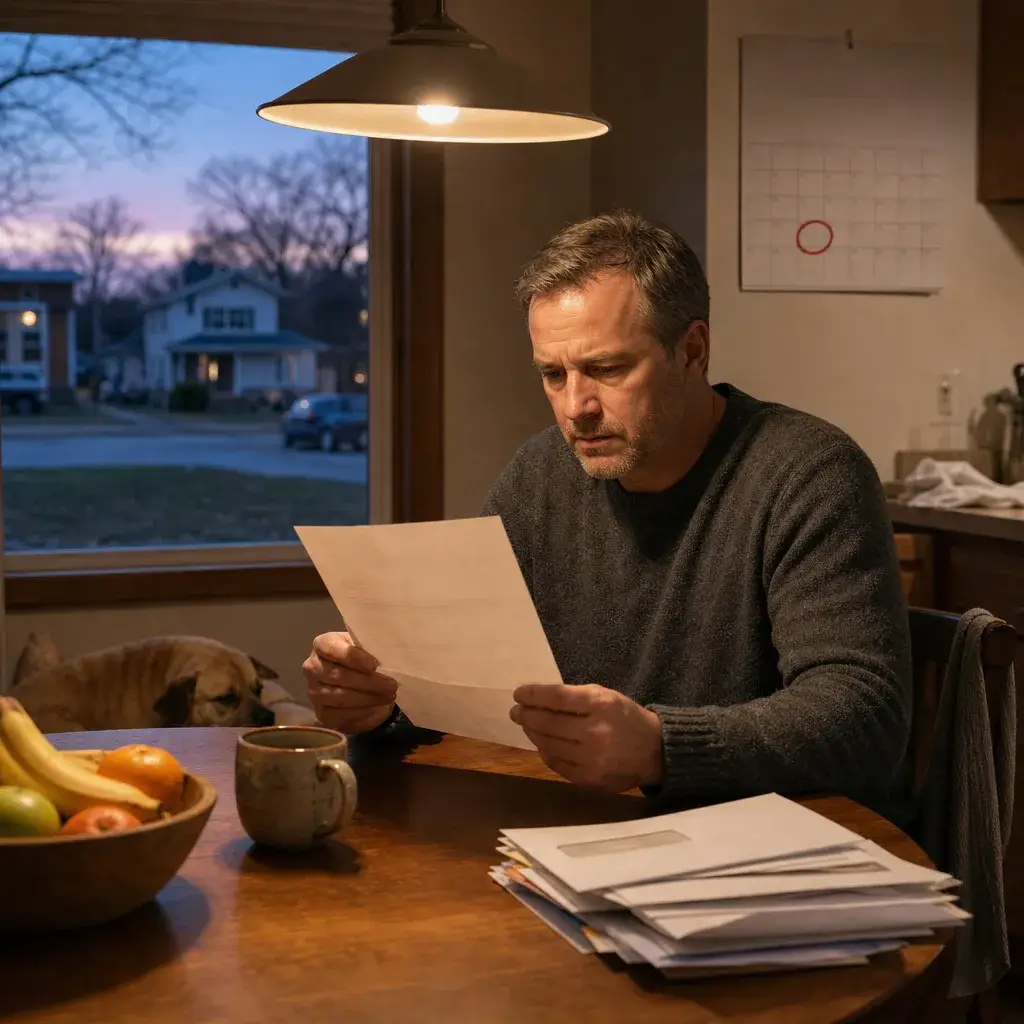
If you’ve fallen behind on your mortgage, you may still be able to sell before the foreclosure date. The sale has to close before the lender’s sale date, and the price has to be enough to pay off what you owe. A cash sale can help because there’s no buyer’s loan to wait on and no repairs to finish first. The sooner you start, the more choices you’ll have.
Many people wait because the letters feel too heavy to open. That’s understandable, but every week you wait leaves less room to sell. If your home sells before the foreclosure is final, you may be able to keep a foreclosure off your record and walk away with any equity that’s left.
Here’s what to do first:
- Open every letter from your lender and find the date of the foreclosure sale, if one is set.
- Call your lender and ask for a payoff amount. That’s the full amount it takes to pay the loan off on a certain date, including late fees.
- Ask your lender whether they offer a repayment plan or a loan change. If you want to keep the house, that may be the better path.
- Write down any second mortgage, home equity loan, unpaid property taxes, or other debts tied to the house.
- Think about talking with a housing counselor or a real estate attorney if you’re not sure what your rights are.
Now hold the payoff amount next to what the house might sell for. If the home is worth more than you owe, a quick cash sale can pay off the loan at closing, and the rest goes to you. Any liens or back taxes get reviewed and explained before you sign. We pay all closing costs, so those won’t come out of what’s left.
Here’s the honest part. If you owe more than the house is worth as-is, a cash sale may not cover the payoff. Our offers depend on the home’s condition, needed repairs, and estimated resale value, and that number may come in under your loan balance. In that case, ask your lender about other options, and talk with an attorney or a Realtor who handles sales where the lender takes less than what’s owed. We’d rather you know that up front than lose time on a deal that can’t close.
When the numbers do work, speed and a firm closing date matter most. You’ll have a written offer within 24 hours of our visit. If we don’t deliver it in that time, we pay you $250. Once you pick a closing date, a closing attorney handles the closing. If closing is late because of us, we pay you $100 per day. On a deadline, you need a buyer who shows up on time, and we put our own money behind it.
You don’t need to fix anything, clean out the house, or explain how you got here. Jason has 30 years of experience buying houses in Huntsville and Madison County, and he’s seen just about every reason a family falls behind. There’s no judgment and no pressure. You’ll just get a clear number so you can decide.
How the Cash Offer Process Works
Selling your house to us comes down to a phone call, one visit, a written offer, and a closing on the date you pick. None of it costs you anything. You can stop at any point before you sign, and you won’t owe us a thing.
Step 1: You call us. Call 256-858-7464 or reach out through huntsvillehousebuyeral.com. Tell us where the house is and a little about what’s going on. We only buy houses in Huntsville and Madison County, so the address is one of the first things we’ll check. You don’t need any papers in hand for this call. We’ll just set a time to see the house.
Step 2: Jason comes to see the house. Jason meets with sellers himself, and he’s the one who makes the offer. You don’t have to clean, fix, or stage anything before he comes. The house can be full of furniture, stained with smoke, or halfway through a repair job someone never finished. We buy as-is, so it’s better for him to see it the way it really is. The visit is free and has no obligation. If you’d feel better with a family member, your attorney, or your Realtor there with you, that’s fine with us.
Step 3: You get a written offer. The clock starts when we see the property, not when you first call. You’ll have a written cash offer within 24 hours of our visit, and the $250 promise backs that up. The number is based on the factors we went over earlier, like condition, repairs, and resale value. There’s no service charge to you, so the offer isn’t reduced by any fee from us. If something about the number doesn’t make sense, it’s fair to ask what went into it. Then take your time. Show it to your family, compare it with what a Realtor thinks you’d net from a listing, and sleep on it if you need to.
Step 4: You review the details before you sign. If you decide to move forward, any mortgages, liens, back taxes, or title issues get looked at and explained before you sign the purchase agreement. That way there aren’t any surprises at the closing table. The buyer named on the contract is Huntsville House Buyer AL LLC, an Alabama LLC, so you’ll know exactly who you’re selling to. Until you sign, nothing is final.
Step 5: You close on your date. You pick a closing date that works for you. It can be soon if you’re up against a deadline, or later if you need time to move or sort through belongings. A closing attorney handles the closing, and we pay all closing costs. Any loan payoffs are taken care of at closing, and our $100-per-day promise covers any delay on our end.
That’s the whole process. There’s no buyer’s loan to wait on, no showings to keep the house ready for, and no repair list sitting between you and a closing date. You know the steps, you know who you’re dealing with, and every choice along the way is yours.
Frequently Asked Questions
You might, depending on your situation, so it’s smart to ask a tax professional before closing. Things like how long you owned the home, whether it was your primary residence, and any gain over what you paid can affect what you owe. An inherited house often has different rules than a home you’ve lived in for years. We can hand you a written offer within 24 hours of our visit, but a tax advisor is the right person to answer what you’ll owe on it.
Condition is usually the biggest reason a house fails to sell. Problems like foundation cracks, an old roof, fire or water damage, or a home packed with belongings often scare off buyers who need a mortgage, because the loan’s appraisal or inspection can kill the deal. That’s exactly the kind of house we buy as-is, without asking you to fix or clean a thing first.
The fastest path is skipping repairs, showings, and the wait for a buyer’s loan to clear. A traditional listing can take months once you add in prep work, open houses, and financing delays. Calling us instead gets you a free visit and a written cash offer within 24 hours of our visit, with a closing date you choose.
- We Buy Houses As-Is
- Locally Owned and Operated
- 30 Years Buying Houses in Madison County
- Fair Cash Offers, No Obligation